
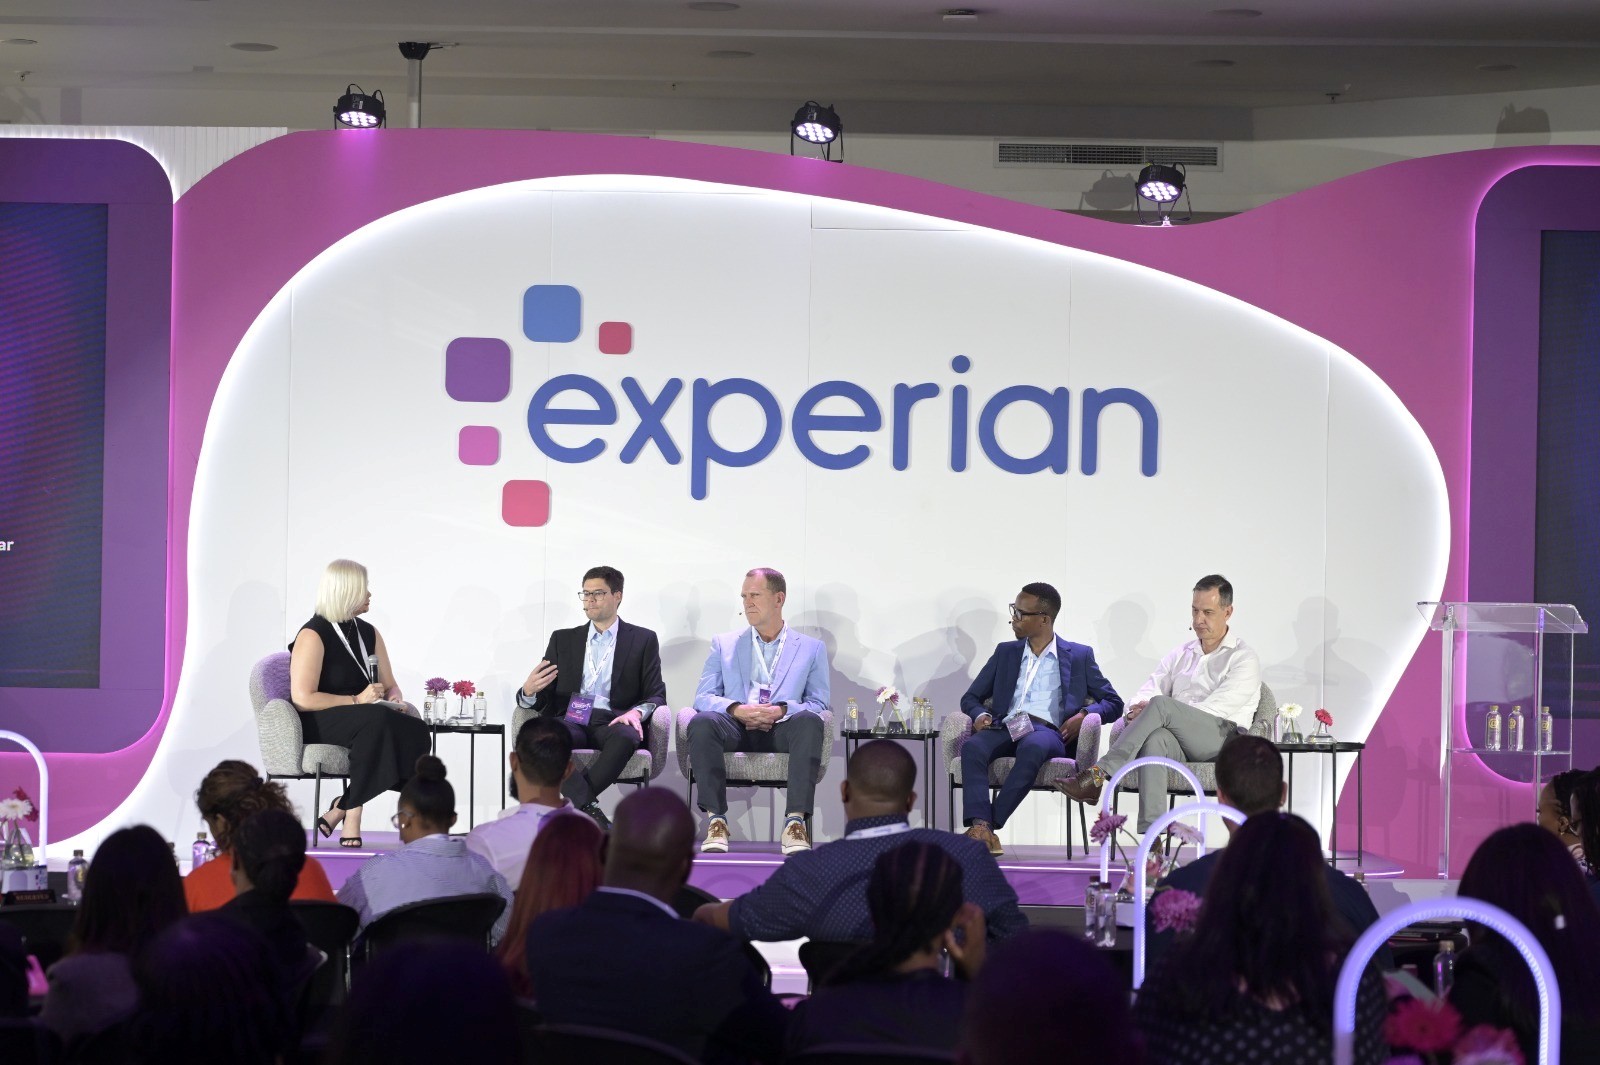
Experian, the global data and technology company, today convened leaders from banking, telecommunications, financial services, retail credit, small business finance, fintech, non-bank lending and insurance at its annual Innovation Summit to examine two developments set to reshape credit and customer decision-making: the rise of agentic AI and the growing role of Buy Now Pay Later (BNPL) data.
Across keynote presentations and industry panels, speakers explored how organisations can move AI from technical capability to practical business value, while building the governance, oversight and trust needed for responsible adoption. The Summit also examined how BNPL information could strengthen visibility into consumers’ financial journeys without creating unfair or unintended outcomes.
“The next phase of innovation will not be defined by technology alone, but by the quality of the decisions it enables,” said Thabo Hermanus, CEO of Experian Southern Africa. “Businesses need to ask how new capabilities can improve customer outcomes, widen responsible access and strengthen confidence. That means pairing innovation with trusted data, transparent processes and clear accountability.”
From AI capability to business reality
A panel facilitated by Bree Caprin, Chief Customer Officer at Experian Southern Africa, explored how AI is evolving from generating information to understanding context, making decisions and taking action. Panellists considered its potential across credit and fraud operations, alongside the risks that arise when autonomous systems act on behalf of consumers or businesses.
The discussion points raised at the Summit echo findings from Experian’s 2026 agentic commerce research. Among the 483 credit-active, digitally literate South African consumers surveyed, 91% said AI agents could help them compare more options than they could manually, while 73% identified reduced control over purchasing decisions as their leading concern. Together, these findings highlight the opportunity for agent-assisted comparison and decision support that keeps consumers firmly in control.
A responsible path for BNPL data
 As newer forms of credit become part of consumers’ financial lives, the Summit also considered how Buy Now Pay Later (BNPL) activity could be reflected responsibly within the wider credit information ecosystem.
A second panel explored how increased visibility of BNPL activity could support better, fairer credit decisions. As BNPL moves beyond being a checkout innovation, panellists considered how it should be classified and interpreted alongside traditional credit information, where the data could add value across financial inclusion, affordability and customer outcomes, and how the industry can avoid inappropriate declines or other unintended consequences.
“BNPL data can offer important context on the financial journeys of younger or underserved consumers who may have limited traditional credit histories,” Hermanus added. “However, more visibility does not automatically produce better decisions. BNPL activity must be understood in context and used appropriately, with safeguards that protect consumers and businesses, while preserving the value of innovation.”
The discussion highlighted the shared responsibilities of BNPL providers, credit bureaus, lenders, regulators, consumer representatives and industry associations. Consistent data definitions, transparent decision-making and a common understanding of how BNPL differs from traditional credit will be critical if reporting is to support inclusion and affordability without penalising consumers unfairly.
“The opportunity is to turn greater intelligence into better outcomes. Organisations that combine innovation with effective governance, explainable decisions and a clear focus on the customer will be best placed to earn trust and grow responsibly,” Hermanus concluded.